Back-to-school season is a good reminder of what a little preparation can accomplish.
Backpacks are ready. Supplies are purchased. Calendars get reorganized. Bedtimes are adjusted. Families use the final weeks of summer to prepare before the pace picks up again.
Accounting and tax firms have a similar opportunity.
September is a natural time to review your firm’s technology, cybersecurity, cyber preparedness, and operational priorities before year-end and the next busy season arrive.
Client demands will increase. Deadlines will get tighter. Seasonal employees may return. Technology will become even more important because there will be less room for interruption.
A little preparation now can prevent a lot of uncertainty later.
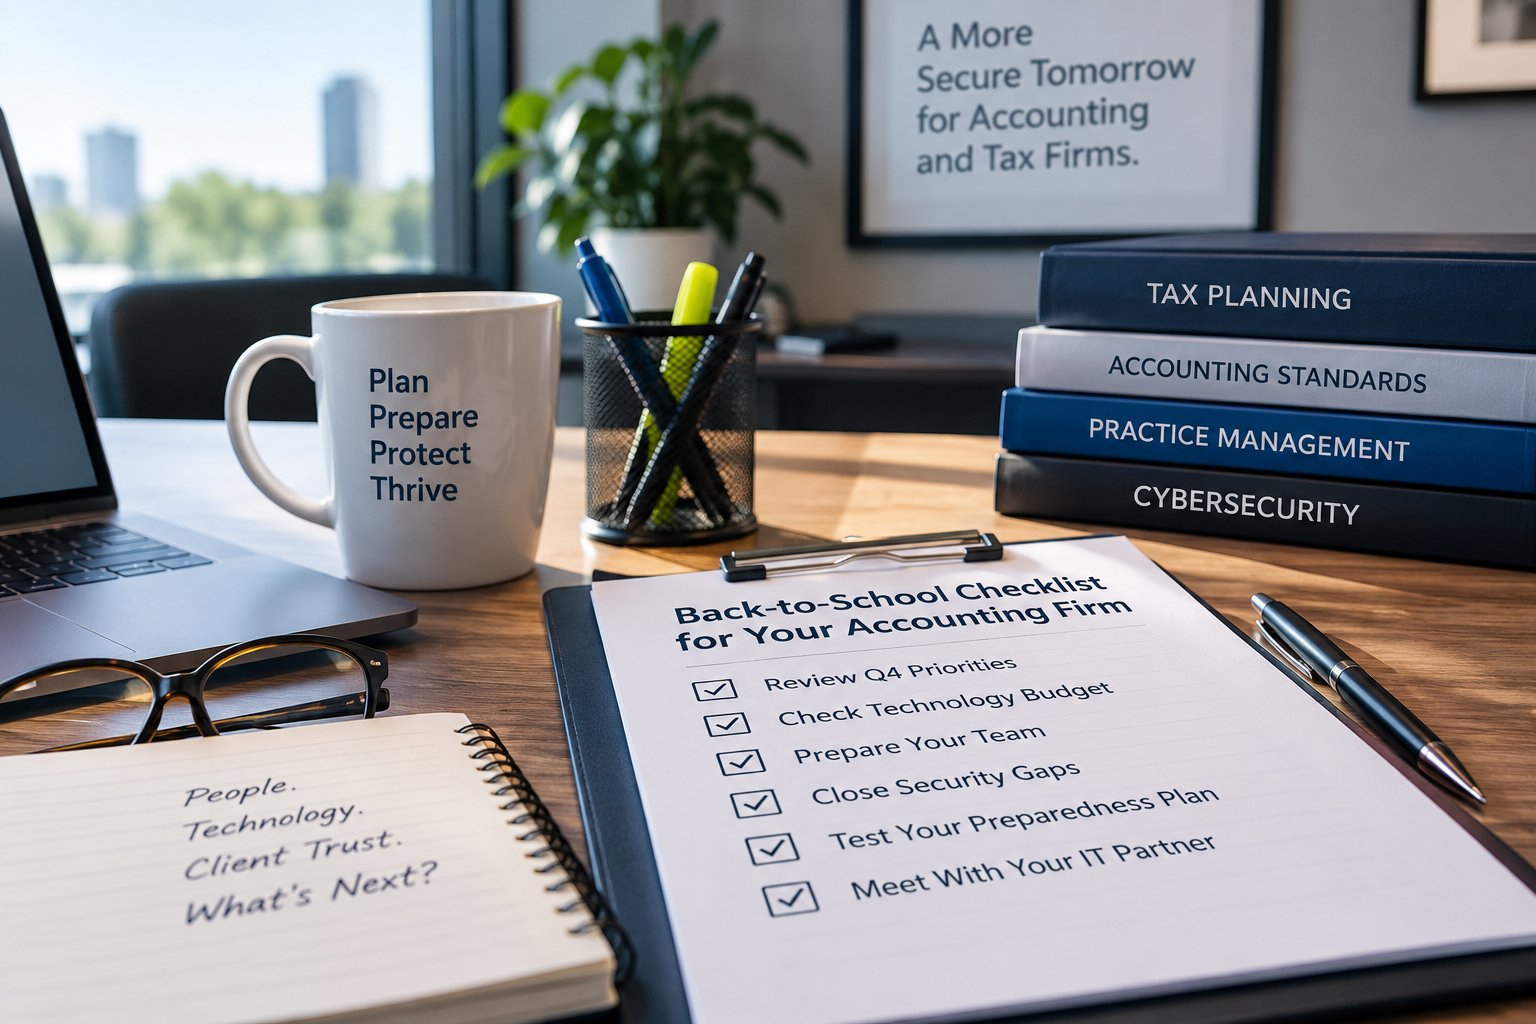
Here is a practical back-to-school checklist for accounting and tax firm leaders.
1. Review Your Accounting Firm’s Q4 Priorities
Start with a simple question:
What absolutely needs to be completed before year-end and busy season?
If you asked three members of your leadership team that question, would you get the same answer?
It’s worth finding out.
Consider:
- Important client commitments.
- Technology projects.
- Cybersecurity improvements.
- Equipment replacements.
- Software changes.
- Staffing needs.
- Operational projects.
- Cyber insurance requirements.
- Projects that need to be finished before busy season.
Accounting firms can easily postpone internal projects because client work understandably comes first.
The problem is that “we’ll get to it later” eventually becomes January.
September gives leadership an opportunity to decide what matters most while there is still time to act.
The goal isn’t to create a longer list.
It’s to create clarity about what belongs at the top of it.
2. Review Your Technology and Cybersecurity Budget
Technology expenses have a habit of appearing at inconvenient times.
A computer needs to be replaced.
A warranty expires.
Software renews.
A vendor changes its pricing.
Seasonal employees need additional equipment and licenses.
Or a cybersecurity improvement that has been discussed for months suddenly can’t wait any longer.
Before year-end budgets are finalized, look ahead.
Ask:
- Are computers or other hardware approaching replacement?
- Are warranties expiring?
- Are software or cloud licenses renewing?
- Will seasonal employees need additional hardware or licenses?
- Are aging systems creating reliability problems?
- Are cybersecurity improvements still waiting for approval?
- Are your backup and recovery capabilities adequate?
- Are there cyber liability risks you’ve identified but haven’t addressed?
- Are there technology projects that should be completed before busy season?
The purpose isn’t simply to predict expenses.
It’s to identify technology and cyber risks while you still have time and options.
3. Make Sure Employees Are Ready for Busy Season
Cyber preparedness isn’t only about technology.
It’s also about people.
Summer can quietly change how an accounting firm operates. Employees take vacations. New people arrive. Someone leaves. Responsibilities shift. Seasonal employees prepare to return.
On paper, the organization may look almost the same.
In practice, it may operate very differently.
Before Q4 gets moving, review your people and access.
Do new employees have the access they need - and only the access they need?
Have former employees’ accounts been disabled?
Do returning seasonal employees understand current technology and security procedures?
Does everyone know how to recognize and report a suspicious email?
Do employees know whom to contact when something doesn’t look right?
Does your team know what to do if an important system becomes unavailable?
Your employees don’t need to become cybersecurity experts.
They do need enough information to recognize a problem, make responsible decisions, and know where to get help.
Prepare people before the pressure arrives.
4. Clean Up Small Technology and Cybersecurity Gaps
Every accounting firm has a list of little things that never quite become urgent.
An old user account that wasn’t disabled.
A computer that should have been replaced.
Outdated documentation.
An employee with access they no longer need.
A backup that hasn’t been tested recently.
A security recommendation that was discussed but never completed.
A vendor account nobody is quite sure who owns.
An incident response plan that hasn’t been reviewed.
Individually, these issues can be easy to tolerate.
But small gaps can become much more important during a cyber incident, insurance renewal, client security questionnaire, system outage, or busy season.
Ask:
What have we been tolerating because it hasn’t caused a problem yet?
Then determine which items are merely inconvenient and which ones create meaningful risk.
You don’t have to fix everything at once.
Understand the risk.
Prioritize what matters.
Document your decisions.
Then work through the list.
5. Ask One Cyber Incident Preparedness Question
September is National Preparedness Month, making it a useful time to consider how your firm would respond to an unexpected disruption.
Ask your leadership team:
If a cyber incident or technology disruption happened tomorrow, would we know what to do?
Imagine:
Your email becomes unavailable.
Your tax software can’t be accessed.
An employee’s Microsoft 365 account is compromised.
A third-party provider experiences an outage.
Ransomware makes critical files unavailable.
What happens next?
Who makes decisions?
Who contacts your technology provider?
How do employees communicate if normal tools aren’t available?
Who communicates with clients?
Where is your cyber insurance information?
Can you access emergency contacts if your normal systems are unavailable?
Do you know which systems need to be restored first?
When was the last time you verified that critical backups could actually be restored?
You don’t need to solve every scenario during one meeting.
You’re trying to determine whether your preparedness is based on evidence or assumptions.
If the answer is, “We know what to do, and here’s how we know,” you’re starting from a strong position.
If the answer begins with, “I think…” or “I’m pretty sure…,” you’ve identified something worth investigating.
Cyber liability isn’t about panic. It’s about proof.
6. Understand Your Accounting Firm’s Cyber Liability Exposure
Cybersecurity conversations often focus on individual tools or requirements.
Do we have MFA?
Are backups running?
Do employees receive security training?
Do we have endpoint protection?
Those are important questions.
But firm leaders also need to understand the bigger picture.
Cyber liability exposure is the business, legal, regulatory, and operational liability a firm faces when its cybersecurity responsibilities aren’t met.
For an accounting or tax firm, that exposure can involve:
- Sensitive client information.
- Business interruption.
- Cyber insurance.
- Employee actions.
- Technology failures.
- Third-party vendors.
- Legal and regulatory responsibilities.
- Client relationships.
- Professional reputation.
This is why checking a cybersecurity requirement off a list doesn’t necessarily tell leadership whether the firm is prepared.
A better question is:
What could this risk mean to our clients and our business if something goes wrong?
That changes cybersecurity from a technical conversation into a business conversation.
The goal isn’t to eliminate every possible risk.
It’s to understand the risks you’re carrying well enough to make informed, responsible decisions about them.
7. Schedule a Quarterly Technology Strategy Meeting
Your technology provider should know more about your firm than what’s sitting in the support queue.
Before year-end, schedule a broader strategy conversation.
Discuss:
- Where the firm is headed in Q4.
- What needs to be ready before busy season.
- Known operational or cybersecurity risks.
- Hardware and software decisions that need to be made.
- Changes involving employees and seasonal staff.
- Critical third-party providers.
- Backup and recovery readiness.
- Incident response planning.
- Cyber liability risks that haven’t been addressed.
- Evidence showing whether important protections are actually working.
And don’t be afraid to ask why something is being recommended.
What risk does it address?
What could that risk mean to the firm?
How important is it compared with other priorities?
What evidence supports the recommendation?
What happens if leadership decides to accept the risk instead?
A useful technology strategy meeting shouldn’t leave leadership with more jargon.
It should leave you with greater clarity about where you stand, what matters, and what should happen next.
Why Is Cybersecurity Preparedness Important for Accounting and Tax Firms?
Accounting and tax firms hold sensitive information that clients expect them to protect.
But cybersecurity preparedness involves more than protecting data.
A cyber incident can affect your ability to work, meet deadlines, communicate with clients, access critical systems, satisfy insurance requirements, and maintain the professional trust you’ve spent years building.
Your firm’s cyber risk also isn’t located in one place.
It can exist across your:
People. Technology. Client information. Operations. Third-party systems.
That’s why cybersecurity needs leadership attention, not just technical attention.
You don’t need to understand every cybersecurity tool.
You need enough information to ask good questions, understand the answers, make responsible decisions, and know what evidence supports those decisions.
Before busy season arrives, an accounting or tax firm should review its technology priorities, employee access, critical systems, backups, incident response procedures, cybersecurity risks, and third-party dependencies.
A simple pre-busy-season checklist includes:
- Identify the technology systems you can’t operate without.
- Review employee and seasonal-worker access.
- Disable accounts that are no longer needed.
- Review aging computers and upcoming software renewals.
- Verify critical backups and recovery procedures.
- Update emergency contacts.
- Review your incident response plan.
- Identify important third-party dependencies.
- Review known cybersecurity and cyber liability risks.
- Document unanswered questions and assign responsibility for resolving them.
You don’t need perfect answers to every question.
You need to know where the uncertainty is.
That’s how assumptions become priorities.
And priorities become a plan.
The Bell Is About to Ring
Families that have a smoother start to the school year are usually the ones that handled the important things before the first bell rang.
They didn’t wait until the night before school to discover there wasn’t a backpack.
Your firm has a similar window.
Q4 is approaching. Year-end will follow. Then busy season will arrive faster than anyone expects.
You don’t need to spend September worrying about everything that could go wrong.
Use it to get clear about what needs to go right.
Review your priorities.
Look ahead at technology spending.
Prepare your people.
Clean up the small gaps you’ve been carrying.
Review your cyber liability exposure.
Talk about what happens during a disruption.
And ask your technology partner to help you understand the risks and decisions ahead.
The goal isn’t perfect security.
It’s being able to say:
We understand where we stand. We understand what matters. We’re making responsible decisions. And we have the evidence to back them up.
Need Help Preparing Your Accounting or Tax Firm for What’s Next?
If this checklist uncovered questions you can’t confidently answer, that’s useful information.
You don’t have to become a technology or cybersecurity expert to make responsible decisions about protecting your clients and your firm.
MTS Consulting Group helps accounting and tax firm leaders understand where they stand, identify technology and cyber liability risks, and turn uncertainty into clear priorities supported by evidence.
That’s our role as a Beacon in the Cyber Storm - helping you see the path more clearly before the crisis hits.
Schedule a Discovery Call with MTS Consulting Group.
It’s a conversation, not a sales pitch. Ask questions, learn how we approach technology and cyber liability, and determine whether MTS is the right partner to help your firm prepare for what comes next.